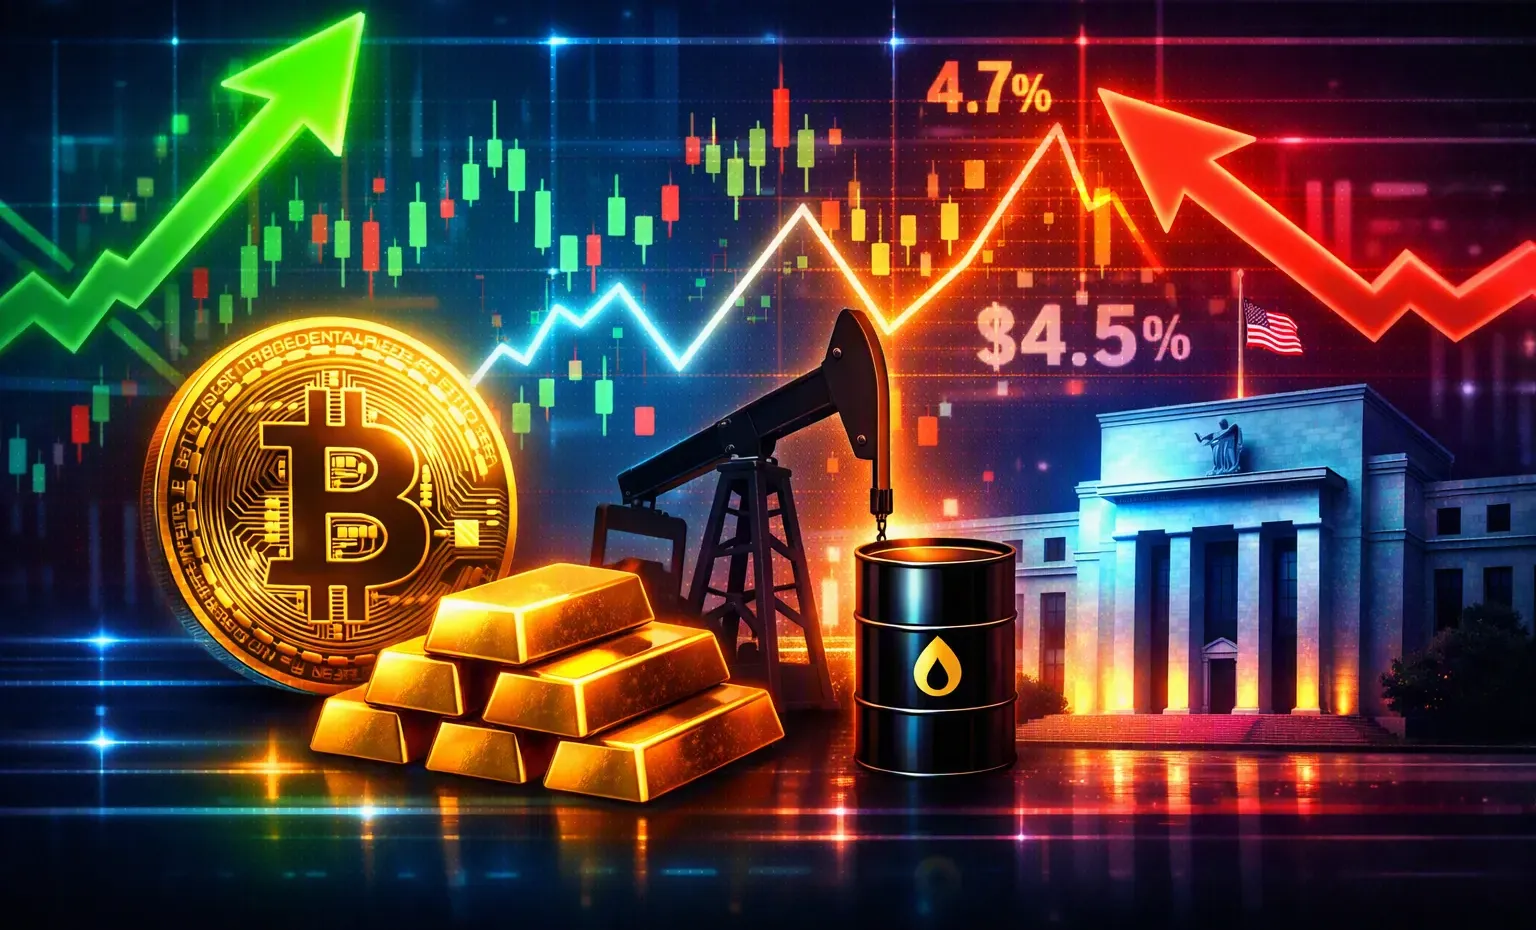
Bitcoin price action September 2026 has been explosive since the latest CPI print, setting off major moves across Bitcoin, gold, oil, US stocks, and the S&P 500.
Bitcoin: A Surge to 87K, Then a Reality Check
Bitcoin exploded upward, touching the 87,000 USD zone before pulling back toward the 83–85K range. The rally was fueled by:
- Strong ETF inflows
- Rising liquidity in risk assets
- Anticipation that Q4 could bring crypto‑friendly policy signals globally
But the pullback was equally telling. As US yields spiked, leveraged long positions unwound and traders reassessed risk exposure. With the 10‑year Treasury yield now around 5.11%, the cost of capital is rising, and speculative assets feel the pressure first.
Still, Bitcoin’s ability to reclaim the mid‑80K range after each dip signals structural demand—especially from institutional allocators who view BTC as a macro hedge rather than a pure risk asset.
Gold: Resilient but Range‑Bound
Gold has been trading near $4,276/oz in spot terms, showing resilience despite rising yields. Historically, gold softens when real yields rise, but geopolitical tensions and elevated energy prices have kept safe‑haven flows alive.
The metal’s performance since CPI has been steady, not spectacular—reflecting a market torn between inflation hedging and yield‑driven opportunity cost.
Oil: Triple‑Digit Prices Add Fuel to Inflation
Oil remains one of the biggest macro drivers. WTI sits near $92/bbl and Brent around $103–104/bbl, driven by:
- Middle East tensions
- Supply disruptions
- Rising global energy demand
Higher oil prices feed directly into CPI components—particularly transportation and energy commodities—which is why the Fed is watching crude closely. Elevated oil is also pushing global sovereign yields higher, reinforcing the hawkish tilt.
US Stocks & S&P 500: Rally Under Pressure
The S&P 500 trades around 7,738–7,749, showing modest gains but facing valuation pressure as yields climb. Equity markets have been surprisingly resilient, supported by strong corporate earnings and AI‑driven growth narratives.
But the bond market is flashing caution. With the 2‑year at 4.85% and 10‑year at 5.11%, the yield curve has repriced sharply higher since CPI, signaling that markets expect more tightening.
Rate Hike Expectations: Markets Price a Hawkish Q4
Fed commentary and futures pricing now suggest at least one more rate hike before year‑end. Markets are pricing nearly three additional hikes by June 2027, reflecting:
- Sticky core inflation
- Strong labor market
- Elevated energy costs
- A Fed committed to restoring price stability
This is why yields have surged for six consecutive months—an extremely rare pattern historically.
Conclusion: The Final Week of September Will Be Conclusive
The last week of September is shaping up to be one of the most decisive macro windows of 2026. With:
- September CPI (Oct 14)
- PCE (Sept 30)
- Jobs Report (Oct 2)
- FOMC (Oct 27–28)
Q4 will begin with major policy decisions from the Fed, Japan, and other global central banks.
Historically, such macro inflection points have been positive for crypto, especially when liquidity cycles stabilize. But the message remains clear:
Stay cautious, stay disciplined, and stick to your fundamentals and strategy. NFA DYOR
Written by
Nadim Zidan
Founder of Celebrity Bee FZ in Dubai. MEA Markets Best Crypto Thought Leader 2026. Writes on digital assets, the Gulf economy and the business of building a name.
More about Nadim →